Income Tax
Annual taxable income → tax due per 2025 brackets.
Income tax, withholding tax, 13th month, and fringe benefits — all using 2025 TRAIN Law brackets. Free, no signup, no ads.
Annual taxable income → tax due per 2025 brackets.
Monthly/ semi-monthly salary → EWT per BIR tables.
Basic salary + months worked → gross 13th month.
Taxable fringe value → 35% FBT (rank & file exempt).
| Taxable Income | Tax Due |
|---|---|
| ₱0 – ₱250,000 | 0% |
| ₱250,001 – ₱400,000 | 15% over ₱250,000 |
| ₱400,001 – ₱800,000 | ₱22,500 + 20% over ₱400,000 |
| ₱800,001 – ₱2,000,000 | ₱102,500 + 25% over ₱800,000 |
| ₱2,000,001 – ₱8,000,000 | ₱402,500 + 30% over ₱2,000,000 |
| Over ₱8,000,000 | ₱2,202,500 + 35% over ₱8,000,000 |
Batch compute, CSV export, historical bracket comparison, and official BIR form pre-fill.
The actual working tool — no mockups.
Official BIR source: bir.gov.ph · Built by Zinvent
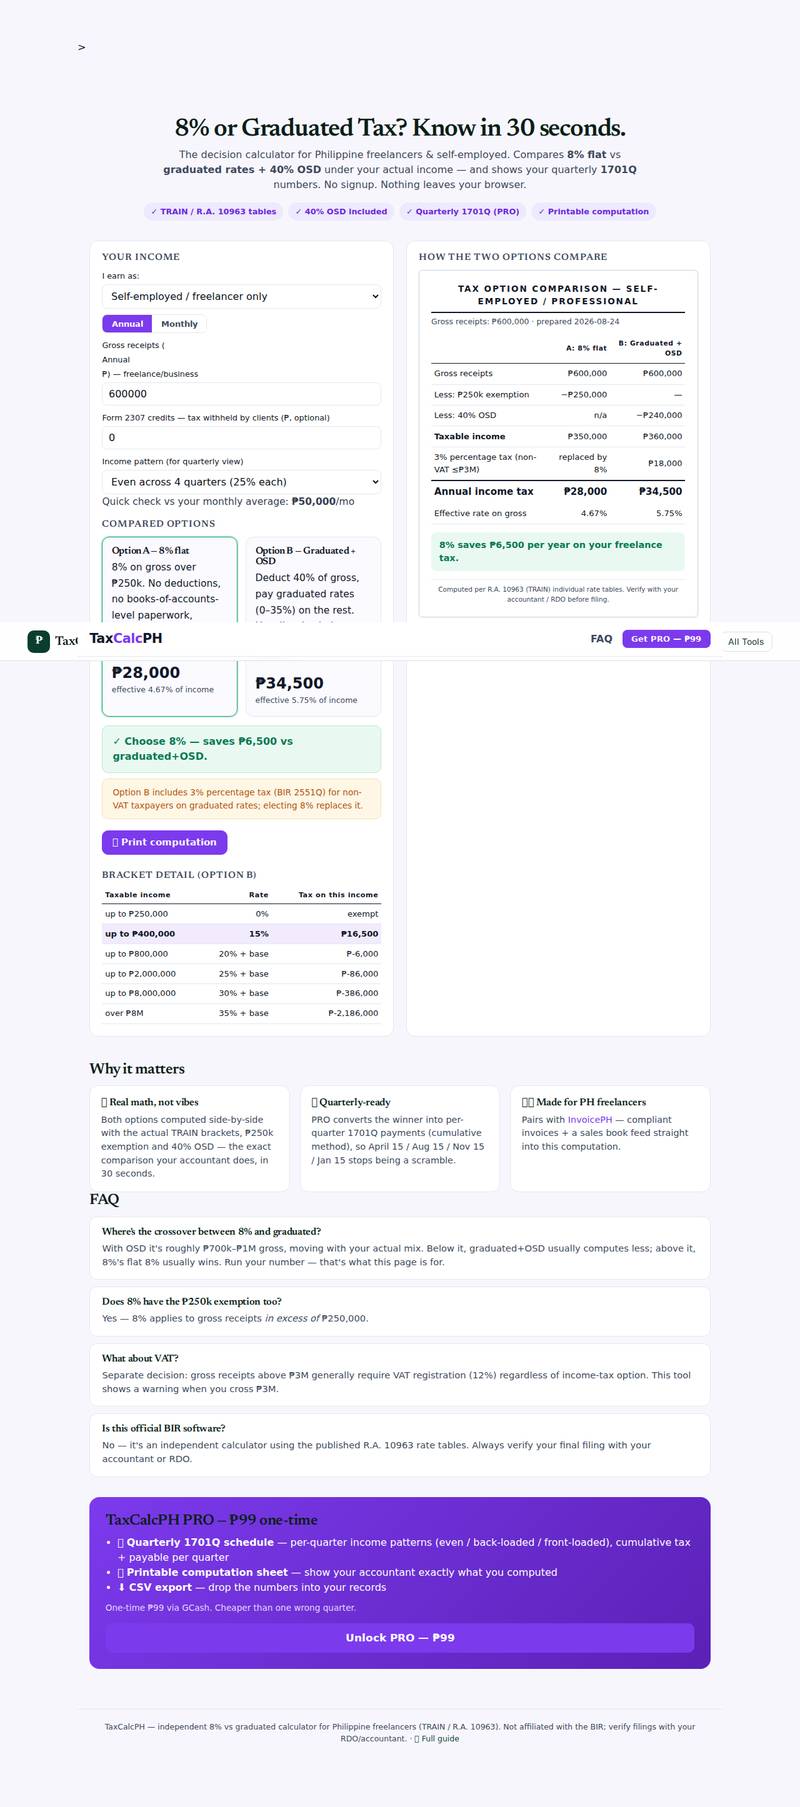
The decision calculator for Philippine freelancers & self-employed. Compares 8% flat vs graduated rates + 40% OSD under your actual income — and shows your quarterly 1701Q numbers. No signup. Nothing leaves your browser.
Quick check vs your monthly average: —/mo
8% on gross over ₱250k. No deductions, no books-of-accounts-level paperwork, simpler. Requires gross ≤ ₱3M.
Deduct 40% of gross, pay graduated rates (0–35%) on the rest. Usually wins below ~₱1M gross; requires books.
| Taxable income | Rate | Tax on this income |
|---|
| A: 8% flat | B: Graduated + OSD | |
|---|---|---|
| Gross receipts | — | — |
| Less: ₱250k exemption | — | — |
| Less: 40% OSD | n/a | — |
| Taxable income | — | — |
| 3% percentage tax (non-VAT ≤₱3M) | replaced by 8% | — |
| Annual income tax | — | — |
| Effective rate on gross | — | — |
Both options computed side-by-side with the actual TRAIN brackets, ₱250k exemption and 40% OSD — the exact comparison your accountant does, in 30 seconds.
PRO converts the winner into per-quarter 1701Q payments (cumulative method), so April 15 / Aug 15 / Nov 15 / Jan 15 stops being a scramble.
Pairs with InvoicePH — compliant invoices + a sales book feed straight into this computation.
With OSD it's roughly ₱700k–₱1M gross, moving with your actual mix. Below it, graduated+OSD usually computes less; above it, 8%'s flat 8% usually wins. Run your number — that's what this page is for.
Yes — 8% applies to gross receipts in excess of ₱250,000.
Separate decision: gross receipts above ₱3M generally require VAT registration (12%) regardless of income-tax option. This tool shows a warning when you cross ₱3M.
No — it's an independent calculator using the published R.A. 10963 rate tables. Always verify your final filing with your accountant or RDO.
One-time ₱99 via GCash. Cheaper than one wrong quarter.